Bank Sector – Q3 2024 Commentary
Categorised in: Bank Sector Commentaries, Commentaries, Q3 2024
|
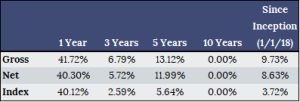
For 3Q, the Bank Sector Strategy returned 18.50% (gross of fees) and 18.20 (net of fees) vs. the Russell 2000® Value Bank Subsector benchmark of 16.63%. Year-to-date the Bank Sector Strategy has returned 15.73% (gross of fees) and 14.86% (net of fees) vs. the Russell 2000® Value Bank Subsector benchmark of 8.94%. Additional performance can be found in the table below.
Data as of 9/30/2024 During the third quarter, we finally began to experience some of the trends we’ve been discussing in prior quarters namely increased bank M&A activity and the start of the Federal Reserve’s interest rate easing cycle. We view both as constructive for bank valuations, and we see both of these trends continuing at least through 2025 regardless of the outcome of the 2024 Presidential election. The 50-basis-point Fed rate cut in September combined with stronger-than-expected employment data in early October, continues to add more credibility to the “soft landing” economic scenario which has positive implications for credit losses across the banking sector. This is also consistent with the conversations we’ve had with many bank management teams in the last quarter that the economy seems to be doing well. With lower interest rates becoming a key defining element of the outlook for banks’ profitability, we began shifting the interest rate exposure of the portfolio well ahead of the September FOMC meeting. Our efforts remain focused on finding institutions with idiosyncratic growth drivers that are misunderstood, underappreciated, or simply overlooked by market participants. For example, during the third quarter, the team performed due diligence in a number of capital raises and M&A transactions not seen for a few years. With a more receptive capital markets environment, management teams are starting to take action, and that gives us the opportunity to evaluate the strategic merits and take advantage of those initiatives we believe will add value. Sincerely, |
|||
|
Brian Hagler Portfolio Manager |
Ithiel Turrado, CFA® Research Analyst |
||
|
|||
|
Important Disclosures Kennedy Capital Management LLC (“KCM”) is a Delaware limited liability company headquartered in Missouri. KCM is registered as an investment adviser with the Securities and Exchange Commission under the Investment Advisers Act of 1940. Registration with the SEC does not imply any level of skill or training. Clients of the Firm include U.S. corporations, pension and profit sharing funds, colleges and universities, trusts, not-for-profit organizations, foundations, and individuals. KCM claims compliance with the Global Investment Performance Standards (GIPS®). GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein. GIPS® are a set of standardized, industry-wide ethical principles that provide investment firms with guidance on calculating and reporting their investment results to prospective clients to ensure fair representation and full disclosure of an investment firm’s performance history. Although the statements of fact and data in this report have been obtained from, and are based upon, sources that the Firm believes to be reliable, we do not guarantee their accuracy, and any such information may be incomplete or condensed. All opinions included in this report constitute the Firm’s judgment as of the date of this report and are subject to change without notice. This report is for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. A complete list of all securities recommended by KCM in the preceding year, a fully compliant GIPS composite report, and the list of composite descriptions are available upon request from KCM at 10829 Olive Blvd., Suite 100. St. Louis, MO, 63141. Bank Sector Strategy Composite is invested in securities of value and growth companies that have a market capitalization ranging from microcap to small cap, generally reflective of the Russell 2000® Value Index Bank Subsector. The U.S. Dollar is the currency used to express performance. Composite specific data provided within this presentation has been calculated from accounts that are discretionary as defined in this paragraph. The assets shown are derived only from discretionary accounts. Non-discretionary accounts, as defined by KCM, are accounts that are not included in the composite due to one or any combination of the following criteria: there were significant cash inflows or outflows within the account; the account’s asset level did not meet the minimum requirement to remain in the composite; the account assets are managed by others using our non-discretionary model. The temporary removal of such an account occurs at the beginning of the month and the account re-enters the composite the month after the criteria has been met. Performance returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross of fee returns reflect the deduction of transaction costs and custodian fees but do not reflect the deduction of investment advisory fees. Net of fee performance is calculated using gross returns less the actual applicable annual management fee applied monthly. Past performance is not indicative of future results. A client’s return will be reduced by the advisory fees as described in Form ADV Part 2A and other expenses incurred by the account. For example, an annual advisory fee of 1% compounded quarterly over 10 years will reduce a gross 14.44% annual return to a net 13.32% annual return. Form ADV Part 2A is available upon request. The performance figures reported herein are unaudited, may be based upon information obtained via electronic data sources (”feeds”) and may be subject to change. Data feeds from many of KCM clients’ selected custodians are obtained through third party sources, and are used to compare custodial data to KCM’s client account records as frequently as daily. Monthly, KCM reviews clients’ account holdings along with cash and share quantities against the custodial statements. In some instances, variances may exist between final audited custodial information and the information KCM obtains via such data feeds. Generally, any such variances are researched and reconciled within thirty days of the period end. The information provided should not be considered a recommendation to purchase or sell any particular security. There is no assurance that any securities discussed herein will remain in a KCM portfolio at the time you receive this letter or that securities sold have not been repurchased. Allocations among industries, sectors and securities may vary and are subject to change without notice. Any securities discussed do not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings. It should not be assumed that any of the industry or sector allocation decisions mentioned, or securities transactions or holdings discussed were or will be profitable, or that the investment recommendations or decisions we make in the future will be profitable or will equal the investment performance of the securities discussed herein. Sector Weightings are subject to change at any time. Sectors are based on the Global Industry Classification Standard (“GICS”) classification scheme and are measured as a percentage of the total composite in terms of asset value as of the date indicated above. Individual client portfolios may be different based on variations in security purchase price and date, and individual client restrictions. GICS was developed by and is the exclusive property and a service mark of Morgan Stanley Capital International, Inc. (”MSCI”) and Standard & Poor’s, a division of The McGraw-Hill Companies, Inc. (”S&P”) and is licensed for the use by KCM. Neither MSCI, S&P, nor any other party involved in making or compiling the GICS or any GICS classifications makes any express or implied warranties or representations with respect to such standard or classification (or the results thereof), and all such parties hereby expressly disclaim all warranties of originality, accuracy, completeness, merchantability, and fitness for a particular purpose with respect to any of such standard or classification. Without limiting any of the foregoing, in no event shall MSCI, S&P, any of their affiliates or any third party involved in making or compiling the GICS or any GICS classifications have any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of the possibility of such damages. Allocations to various assets classes change over time and deviate from any stated or targeted percentages of a total portfolio as a result of market conditions and reallocation decisions. Therefore, nothing herein reflects a static portfolio allocation that will remain the same or match stated target allocations of asset classes. Russell Investment Group is the source and owner of the Russell Index data contained or reflected in this material and all trademarks and copyrights related thereto. The presentation may contain confidential information and unauthorized use, disclosure, copying, dissemination or redistribution is strictly prohibited. This is a presentation of Kennedy Capital Management. Russell Investment Group is not responsible for the formatting or configuration of this material or for any inaccuracy in Kennedy Capital Management’s presentation thereof. The Russell 2000® Value Index Bank Subsector measures the performance of micro- to small-cap value segment of the U.S. equity universe. It includes those Russell 2000® companies with lower price-to-book ratios and lower forecasted growth values. The Russell 2000® Value Index Bank Subsector is constructed to provide a comprehensive and unbiased barometer for the micro-cap and small-cap value segment. The Index is completely reconstituted annually to ensure larger stocks do not distort the performance and characteristics of the true small-cap opportunity set and that the represented companies continue to reflect value characteristics. The investment portfolios underlying the Index are different from the investments in the portfolios managed by the Firm. The Russell 2000® Value Index Bank Subsector defined by FTSE Russell using the Industry Classification Benchmark (ICB) standard. ICB is a globally recognized standard, operated and managed by FTSE Russell for categorizing companies and securities using a detailed and comprehensive structure for sector and industry analysis, facilitating the comparison of companies across four levels of classification and national boundaries. The classification system allocates companies to the Subsector whose definition closely describes the nature of its business as determined from the source of its revenue or the source of the majority of its revenue where available. FTSE Russell is responsible for maintaining ICB, and for the classification of all companies within ICB. The Russell 2000® Value Index Bank Subsector is used as the benchmark. The Index is unmanaged and represents total returns including reinvestment of dividends. The benchmark is used for comparative purposes only and generally reflects the comparable risk or investment style of the Firm’s strategy. The investment portfolios underlying the Index are different from the investments I the portfolios managed by the Firm. Certain accounts may also use other benchmarks not listed in the GIPS composite report. The Verification and Performance Examination Report does not cover the benchmark returns included in the GIPS composite report. Investors cannot invest directly in an Index. |
|||