Mid Cap Value – Q4 2024 Commentary
Categorised in: Commentaries, Mid Cap Value Commentaries, Q4 2024
|
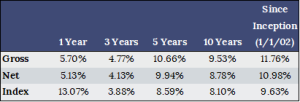
Equity market performance was mixed in the 4th quarter of 2024. The Russell Midcap® Value (RMV) Index declined 1.7%, while the S&P 500® Index (S&P) rose 2.4%. Performance was robust in November (RMV +7.4%) following Donald Trump’s victory in the 2024 Presidential election. Potential for less regulation, increased M&A activity, and faster economic growth under a Trump administration are seen as positive tailwinds for midcap equities. Market performance reversed in December, however, with the RMV down 7.3%. A more cautious tone from the Federal Reserve (fewer interest rate cuts now expected in 2025) and a sharp increase in longer-dated bond yields pressured equity markets. From a sector perspective (within the RMV), Energy +9.7% and Financials +6.3% were standout performers. On the downside, Health Care and Materials were notable underperformers, each down -10.4%. The Kennedy Capital Mid Cap Value (MCV) composite decreased 4.7% (net of fees) during the quarter, underperforming the RMV by 2.95%. Additional performance information is included in the table below.
Data as of 12/31/2024 Within the MCV composite, stock selection in the Health Care +37 basis points and Consumer Staples +23 basis points sectors were the largest contributors to 4th quarter performance. Conversely, stock selection in the Industrials and Consumer Discretionary sectors negatively impacted performance, detracting 103 and 98 basis points, respectively.
Source: FactSet Research Systems, Inc. 2024 was a strong year for US equity markets, with most major indices posting double-digit gains. The RMV Index was no exception, posting a 13.1% gain. This compares to the Index’s 10-year average return of +8.1%. As can be seen in the chart above, monthly performance was highly volatile. Strong performance in July +6.0% and November +7.4% – buoyed by excitement around rate cuts and Trump’s presidential election victory – were partially offset by poor returns in April -5.2% and December -7.3%. Recapping what happened in 2024: – Federal Reserve Rate Cuts: After 2+ year tightening cycle (starting in March of 2022), the Federal Reserve began lowering interest rates in September of 2024. The decision to cut rates was prompted by softening inflation trends. – Steady Economic Activity: Despite fears of a hard landing, the US economic activity was steady in 2024. Unemployment levels have stayed low and consumer spending has proven resilient despite pressures from higher interest rates and inflation. – Presidential Election: US equity markets reacted favorably to Donald Trump’s victory in the 2024 Presidential election. Bulls see potential for accelerating economic growth, less regulation, and an increase in M&A activity. Bears see economic risk from aggressive tariff policies and potential for a re-accelerating inflation. – Proliferation of Artificial Intelligence Technology: Numerous practical applications of AI have emerged, focused on areas such as software coding optimization, cloud resource management, call center operations, fraud prevention, and equipment maintenance. AI demand tailwinds benefited numerous companies (and equity performance) across Tech, Industrials, and Utilities. We are optimistic on mid cap equity markets in 2025. Tailwinds include continued economic growth (underpinned by steady employment trends), potential for a more lenient regulatory backdrop (particularly for financials) under Trump, and a more favorable short-term interest rate backdrop. Offsets to these tailwinds include higher-for-longer longer-term rates (due to sticky inflation expectations), and potential for supply chain disruption from changes in tariff policy. Taking these factors into account, we expect mid cap equities to achieve steady earnings growth in 2025. Regardless of the economic or market backdrop, our philosophy and process remain the same: 1) Identify high quality businesses that can compound in value over time. 2) Invest in those businesses when market expectations are low. 3) Leverage the power of compounding to help drive attractive long-term portfolio returns. This sounds simple, but it’s not easy. By staying disciplined to our process, we aim to construct a portfolio of companies that in aggregate exhibit favorable fundamental attributes relative to the overall market, while seeking valuation levels that give us a sufficient margin of safety. We believe this is a winning recipe for portfolio returns over the long term. We welcome the opportunity to discuss any questions or concerns you may have, and we thank you for the opportunity you have given us to manage your account. Sincerely, |
|||
|
Gary Kauppila, CFA® Portfolio Manager |
Christian McDonald, CFA® Assistant Portfolio Manager |
||
|
|||
|
Important Disclosures Kennedy Capital Management LLC (“KCM”) is a Delaware limited liability company headquartered in Missouri. KCM is registered as an investment adviser with the Securities and Exchange Commission under the Investment Advisers Act of 1940. Registration with the SEC does not imply any level of skill or training. Clients of the Firm include U.S. corporations, pension and profit sharing funds, colleges and universities, trusts, not-for-profit organizations, foundations, and individuals. KCM claims compliance with the Global Investment Performance Standards (GIPS®). GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein. GIPS® are a set of standardized, industry-wide ethical principles that provide investment firms with guidance on calculating and reporting their investment results to prospective clients to ensure fair representation and full disclosure of an investment firm’s performance history. Although the statements of fact and data in this report have been obtained from, and are based upon, sources that the Firm believes to be reliable, we do not guarantee their accuracy, and any such information may be incomplete or condensed. All opinions included in this report constitute the Firm’s judgment as of the date of this report and are subject to change without notice. This report is for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. A complete list of all securities recommended by KCM in the preceding year, a fully compliant GIPS composite report, and the list of composite descriptions are available upon request from KCM at 10829 Olive Blvd., Suite 100. St. Louis, MO, 63141. The Mid Cap Value Composite invests in US equity securities and ADRs with market capitalizations that are reflective of the Russell Midcap® Value Index. The portfolio manager focuses on companies with a demonstrated ability to generate above-average returns on invested capital. Within that universe, the manager seeks to identify undervalued companies with opportunities to reinvest cash flows at rates of return in excess of their cost of capital. For comparison purposes the composite is measured against the Russell Midcap® Value Index. The U.S. Dollar is the currency used to express performance. Composite specific data provided within this presentation has been calculated from accounts that are discretionary as defined in this paragraph. The assets shown are derived only from discretionary accounts. Non-discretionary accounts, as defined by KCM, are accounts that are not included in the composite due to one or any combination of the following criteria: there were significant cash inflows or outflows within the account; the account’s asset level did not meet the minimum requirement to remain in the composite; the account assets are managed by others using our non-discretionary model. The temporary removal of such an account occurs at the beginning of the month and the account re-enters the composite the month after the criteria has been met. Performance returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross of fee returns reflect the deduction of transaction costs and custodian fees but do not reflect the deduction of investment advisory fees. Net of fee performance is calculated using gross returns less the actual applicable annual management fee applied monthly. Past performance is not indicative of future results. A client’s return will be reduced by the advisory fees as described in Form ADV Part 2A and other expenses incurred by the account. For example, an annual advisory fee of 1% compounded quarterly over 10 years will reduce a gross 14.44% annual return to a net 13.32% annual return. Form ADV Part 2A is available upon request. The performance figures reported herein are unaudited, may be based upon information obtained via electronic data sources (”feeds”) and may be subject to change. Data feeds from many of KCM clients’ selected custodians are obtained through third party sources, and are used to compare custodial data to KCM’s client account records as frequently as daily. Monthly, KCM reviews clients’ account holdings along with cash and share quantities against the custodial statements. In some instances, variances may exist between final audited custodial information and the information KCM obtains via such data feeds. Generally, any such variances are researched and reconciled within thirty days of the period end. The information provided should not be considered a recommendation to purchase or sell any particular security. There is no assurance that any securities discussed herein will remain in a KCM portfolio at the time you receive this letter or that securities sold have not been repurchased. Allocations among industries, sectors and securities may vary and are subject to change without notice. Any securities discussed do not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings. It should not be assumed that any of the industry or sector allocation decisions mentioned, or securities transactions or holdings discussed were or will be profitable, or that the investment recommendations or decisions we make in the future will be profitable or will equal the investment performance of the securities discussed herein. Sector Weightings are subject to change at any time. Sectors are based on the Global Industry Classification Standard (“GICS”) classification scheme and are measured as a percentage of the total composite in terms of asset value as of the date indicated above. Individual client portfolios may be different based on variations in security purchase price and date, and individual client restrictions. GICS was developed by and is the exclusive property and a service mark of Morgan Stanley Capital International, Inc. (”MSCI”) and Standard & Poor’s, a division of The McGraw-Hill Companies, Inc. (”S&P”) and is licensed for the use by KCM. Neither MSCI, S&P, nor any other party involved in making or compiling the GICS or any GICS classifications makes any express or implied warranties or representations with respect to such standard or classification (or the results thereof),and all such parties hereby expressly disclaim all warranties of originality, accuracy, completeness, merchantability, and fitness for a particular purpose with respect to any of such standard or classification. Without limiting any of the foregoing, in no event shall MSCI, S&P, any of their affiliates or any third party involved in making or compiling the GICS or any GICS classifications have any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of the possibility of such damages. Allocations to various assets classes change over time and deviate from any stated or targeted percentages of a total portfolio as a result of market conditions and reallocation decisions. Therefore, nothing herein reflects a static portfolio allocation that will remain the same or match stated target allocations of asset classes. Russell Investment Group is the source and owner of the Russell Index data contained or reflected in this material and all trademarks and copyrights related thereto. The presentation may contain confidential information and unauthorized use, disclosure, copying, dissemination or redistribution is strictly prohibited. This is a presentation of Kennedy Capital Management. Russell Investment Group is not responsible for the formatting or configuration of this material or for any inaccuracy in Kennedy Capital Management’s presentation thereof. The Russell Midcap® Value Index measures the performance of the mid-cap value segment of the U.S. equity universe. It includes those Russell Midcap® Index companies with relatively lower price-to-book ratios, lower I/B/E/S forecast medium term (2 year) growth and lower sales per share historical growth (5 year). The Russell Midcap® Value Index is constructed to provide a comprehensive and unbiased barometer of the mid-cap value market. The Index is completely reconstituted annually to ensure larger stocks do not distort the performance and characteristics of the true mid-cap value market. The Russell Midcap® Value Index is used as the benchmark. The Index is unmanaged and represents total returns including reinvestment of dividends. The benchmark is used for comparative purposes only and generally reflects the comparable risk or investment style of the Firm’s strategy. The investment portfolios underlying the Index are different from the investments in the portfolios managed by the Firm. Certain accounts may also use other benchmarks not listed in the GIPS composite report. The Verification and Performance Examination Report does not cover the benchmark returns included in the GIPS composite report. Investors cannot invest directly in an Index. The S&P® 500 is widely regarded as the best single gauge of large-cap U.S. equities. According to our Annual Survey of Assets, an estimated USD 15.6 trillion is indexed or benchmarked to the index, with indexed assets comprising approximately USD 7.1 trillion of this total (as of Dec. 31, 2021). The index includes 500 leading companies and covers approximately 80% of available market capitalization. |
|||